How central banks learned to steer
Awarded to Robert E. Hall and Michael Woodford “for microeconomic foundations of macroeconomic stabilisation”.
1Pick your depth
What was the 2026 Nobel Prize in Economics awarded for?
The 2026 economics prize rewards the models that central banks and finance ministries now use to smooth out booms and recessions. After the 1970s, when the old models failed and inflation ran out of control, Robert E. Hall showed that household spending follows people's expectations of their future income, and Michael Woodford built a complete New Keynesian model from the decisions of individual households and firms. Because those decisions look ahead, what a central bank says about its future plans can steer the economy today.
2Guess first
In the 1970s, governments followed the textbook: when unemployment rose, they stimulated the economy. Instead of falling, unemployment stayed high and inflation took off. What had gone wrong with the textbook?
How close were you?
Economists spent years searching for signals that could forecast how much households will spend next year. Robert E. Hall predicted that every such search would fail. Why would that be good news?
How close were you?
3Learn it at ELI5
ELI5 done
Read the transcript
In the 1970s, a family went shopping, and the groceries cost more again. Then a parent lost a job. The grown-ups who steer the economy gave it a push. This time, the push only made prices climb faster. Robert E. Hall showed that families spend by thinking about tomorrow. Michael Woodford built a model where shops look ahead too. When the central bank clearly explains its plan, everyone adjusts early. Central banks now use models like his. Hall and Woodford share the 2026 prize in economic sciences.
Undergrad done
Read the transcript
For years, economists hunted for a signal that could forecast household spending. None of them worked. In 1978, Robert E. Hall turned the search upside down. If spending follows expected income, it changes only when news arrives. News cannot be predicted, so neither can those changes. The US data largely agreed. With Fredric Mishkin, Hall later found that about 80 percent of families fit, while the rest lived hand to mouth. Michael Woodford placed Hall's household inside a model of the whole economy. His firms change prices only now and then, so they look ahead as well. With these models, the pandemic and recent energy crises did less lasting damage than the 1970s. Hall and Woodford split the 2026 prize in economic sciences equally.
Expert done
Read the transcript
An energy price spike hits, and output falls. Michael Woodford's model tells the central bank to raise rates anyway. His output gap is measured against natural output, the level with flexible prices. The shock cuts natural output even more, so the gap turns positive and inflation pressure builds. The model's demand side is Robert E. Hall's 1978 consumption Euler equation. Hall showed that past income barely predicts changes in consumption. Firms that reset prices only occasionally give a forward-looking Phillips curve, and an interest-rate rule closes the system. Since inflation depends on expected future gaps, the expected path of rates becomes an instrument. Woodford and others proposed forward guidance, which the US used at the zero lower bound from 2008 to 2015. Sweden's central bank runs its own extension, called MAJA. Hall and Woodford each receive half of the 2026 prize in economic sciences.
An economy has good years and bad years. In bad years, many people lose their jobs. In very good years, prices can climb so fast that money buys less and less. Governments and central banks try to keep things steady, a bit like a driver who brakes before a sharp bend and speeds up on a straight road.
In the 1970s, the old instructions for driving the economy stopped working. Prices rose quickly while jobs disappeared at the same time. Robert E. Hall and Michael Woodford helped write new instructions. They started with ordinary people and shops, who all think about tomorrow when they decide what to do today.
Telling people the plan helps
If a family expects to earn more next year, it spends a little more now. If a shop expects its costs to rise, it sets its prices a little higher. So when a central bank clearly explains what it will do next, people adjust in advance, and the economy starts moving in the right direction.
Since John Maynard Keynes, almost a century ago, governments have tried to even out the business cycle. In a downturn they cut interest rates or raise the budget deficit to boost demand. In a boom they do the opposite. This is stabilisation policy, and its aim is to keep the economy away from both high unemployment and runaway inflation.
The traditional Keynesian models worked out the doses from statistical links between big aggregates. One is the Phillips curve: inflation tends to be low when unemployment is high, and the reverse. Another is that consumption follows current disposable income. During the oil crises of the 1970s these links broke. Inflation rose while unemployment rose too, stimulus arrived at the wrong time, and the West went through a decade of low growth and high inflation. Robert E. Lucas, Jr., the 1995 laureate, argued that the models needed microfoundations: they had to be built from how individual households and firms actually decide.
Spending follows expectations
Earlier work suggested that households base their spending on what they expect to earn in the future, but expectations cannot be observed. Robert E. Hall turned the problem around. If spending already reflects expectations, it will only change when new information arrives, and genuine news cannot be predicted. So changes in consumption should be unpredictable. The data agreed. In 1982 Hall and Fredric Mishkin found that around 80 per cent of households in their sample behaved this way, while the rest lived hand to mouth.
Michael Woodford built the full model. In his 2003 book Interest and Prices he set out a New Keynesian model with three equations. Households decide how much to spend by looking at expected income and the interest rate, using Hall's result. Firms set prices knowing they cannot change them often, so prices are sticky and every price decision looks ahead. A central bank steers the whole system with its interest rate. Woodford also introduced the output gap, the distance between actual output and the output the economy would produce if prices adjusted freely. Policy aims to push that gap toward zero.
Because households and firms look ahead, credibility and transparency become policy tools in their own right. A central bank that explains what it plans to do with rates shifts expectations, and with them spending and price setting, before it moves. According to the prize committee, this approach helped policymakers respond to the pandemic and the recent energy crises far better than in the 1970s, with shorter episodes of recession and high inflation.
The Lucas critique left macroeconomics with a demand that was easy to state and hard to meet. Policy models had to rest on behaviour that stays invariant when policy changes, which meant deriving aggregate relationships from optimising households and firms. They also had to stay simple enough for central banks to use. The 2026 prize rewards two contributions that made this possible: Hall's treatment of consumption under rational expectations, and Woodford's assembly of a tractable, microfounded model of monetary policy.
A benchmark from an unpredictability result
Friedman's permanent income hypothesis had been implemented with adaptive expectations, so past income was expected to move consumption. Hall showed in 1978, in the Journal of Political Economy, that under rational expectations the household Euler equation makes consumption, in the simplest case, a martingale: given today's consumption, nothing else known today should predict tomorrow's, so changes are driven only by news. In quarterly US data, income and its lags had minimal predictive power, though stock prices had some. Later work found more predictability, but the martingale became the null hypothesis. Deviations from it now measure frictions such as borrowing constraints, and Hall and Mishkin's 1982 estimate on panel data for 2,309 families put the hand-to-mouth share at about 20 per cent.
Woodford's Interest and Prices (2003) consolidated earlier work, including his microfounded sticky-price model with Julio Rotemberg, into what is now the textbook three-equation system. A dynamic IS curve is the log-linearised household Euler equation: the output gap depends on the expected future gap and on the real interest rate relative to the natural rate. A New Keynesian Phillips curve follows from staggered price setting of the Calvo type: inflation depends on expected future inflation and the output gap. An interest-rate rule closes the model. Following Wicksell, whose 1898 book his title translates, Woodford framed policy as setting an interest rate relative to a natural rate, rather than as controlling the money supply. He called the framework neo-Wicksellian.
Why a supply shock can call for tighter policy
The relevant gap is measured from natural output, the level that would prevail with fully flexible prices, and not from a smooth trend. A negative supply shock, such as an energy price spike, lowers natural output. If actual output falls by less, the gap turns positive even though demand has not risen, and inflation pressure builds. The model then prescribes a cooling response, such as higher rates, where the traditional Keynesian framework read falling output as a reason to stimulate. The prize committee credits this insight with the better handling of recent supply shocks compared with the 1970s.
Forward-looking pricing turns the expected path of policy rates into the main channel of transmission. Inflation today depends on expected future gaps, so a central bank acts through what it commits to as much as through the current rate. That is why credibility and clear communication became central to modern central banking. It also opened a new instrument: forward guidance, proposed by Woodford and others, let central banks stimulate demand by promising low future rates when current rates could not fall below zero, as in the United States from 2008 to 2015. The framework was a starting point, not a final word. Richer versions add wage rigidities, hand-to-mouth households in line with Hall's benchmark, and country detail, and Woodford's own recent work relaxes rational expectations. The three-equation core has nonetheless remained the common language of stabilisation policy.
Your next rate decision runs through this model
According to the prize committee, New Keynesian models are now used by central banks and finance ministries around the world, and there is no viable alternative. Sweden's central bank runs its own version adapted to Swedish conditions. So the next time your central bank sets its policy rate, one input in that decision was very likely calculated with a model built on the work of Hall and Woodford.
4Check yourself
What went wrong with traditional Keynesian models during the oil crises of the 1970s?
What did Robert E. Hall predict about changes in household consumption?
In Woodford's model, why do a central bank's credibility and communication matter so much?
Key terms
- Stabilisation policy
- Measures by central banks and governments, such as changes in interest rates, taxes or transfers, that aim to even out booms and recessions.
- Microfoundations
- Building a model of the whole economy from the decisions of individual households and firms, instead of from statistical links between aggregates.
- New Keynesian model
- A macroeconomic model built on microfoundations, with forward-looking households and firms and prices that adjust only slowly. Woodford's three-equation version is the prototype.
- Sticky prices
- Prices that firms change only now and then because adjusting them is costly. They are why changes in demand affect output in the short run.
- Output gap
- The difference between actual output and natural output, the level the economy would produce if prices adjusted freely. Stabilisation policy aims to bring it to zero.
- Natural rate of interest
- The interest rate that neither stimulates nor holds back spending. The idea goes back to Knut Wicksell; Woodford built policy around setting rates relative to it.
- Hand-to-mouth household
- A household that spends its current income because it cannot borrow or has no savings, so it does not follow the forward-looking benchmark Hall set out.
The laureates
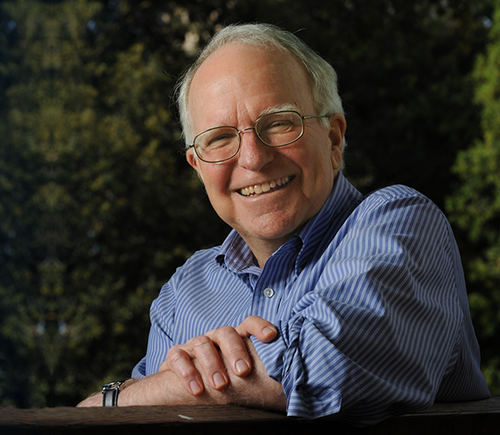
Born in Palo Alto in 1943, Hall earned his PhD at MIT in 1967 under Robert Solow and is a professor at Stanford. His 1978 article showed that if spending depends on expectations, changes in consumption should be impossible to predict, and the data agreed. He has chaired the committee that dates the start and end of US recessions since 1978.
Born in Chicopee, Massachusetts, in 1955, Woodford took a law degree at Yale before his economics PhD at MIT in 1983. He is a professor at Columbia. His 2003 book Interest and Prices set out the three-equation New Keynesian model that became the prototype for the models central banks use today.
Sources
Facts are pinned from the official Nobel Prize API. The explanations were written from these sources:
- The Prize in Economic Sciences 2026, popular information (NobelPrize.org)
- The Prize in Economic Sciences 2026, press release (NobelPrize.org)
- Microeconomic foundations of macroeconomic stabilization, scientific background (NobelPrize.org)
- Robert Hall (economist) (Wikipedia)
- Michael Woodford (Wikipedia)
- New Keynesian economics (Wikipedia)